


Risk Management · Lesson 05 of 15 · Reviewed November 10, 2026
A loss and an equal percentage gain do not cancel because they apply to different bases. An account falling from $10,000 to $8,000 loses 20%. A later 20% gain on $8,000 adds $1,600, leaving $9,600. Regaining the original $10,000 requires a 25% gain from the lower level.
This lesson explains peak-to-current drawdown, recovery arithmetic, and the difference between a simple equity comparison and a complete performance report. The exercise uses an entered historical peak and current equity without deposits or withdrawals. It does not predict how long recovery will take or whether it will occur.
1. Define the reference peak
A drawdown compares a later equity value with a prior high-water reference. The peak must precede the current observation in the study. Choosing an arbitrary larger number that never represented the account creates a target gap, not a measured historical drawdown.
Specify whether equity includes open marked positions, cash, debt, and accrued charges. A closed-trade-only balance can hide a large unrealized decline. A mark-to-market value can change before liquidation and may differ from actual exit proceeds. Both conventions need explicit labels.
The worksheet takes a supplied peak and current value. It cannot verify that the peak occurred, that all holdings were valued consistently, or that cash flows were absent. Those data responsibilities remain with the learner.
2. Calculate the dollar and percentage decline
Dollar decline equals peak minus current equity when current is below the peak. Drawdown percent divides that decline by peak and multiplies by 100. For peak $10,000 and current $8,000, the decline is $2,000 and drawdown 20%.
The denominator is the peak, not current equity. Dividing $2,000 by $8,000 gives 25%, which answers the recovery question instead. Naming the denominator prevents the two measurements from being confused.
If current equity equals the peak, drawdown is zero. If it exceeds the supplied reference, the worksheet reports no current drawdown against that old reference and identifies that the current value establishes a new high relative to the input. A full historical series would update its high-water mark accordingly.
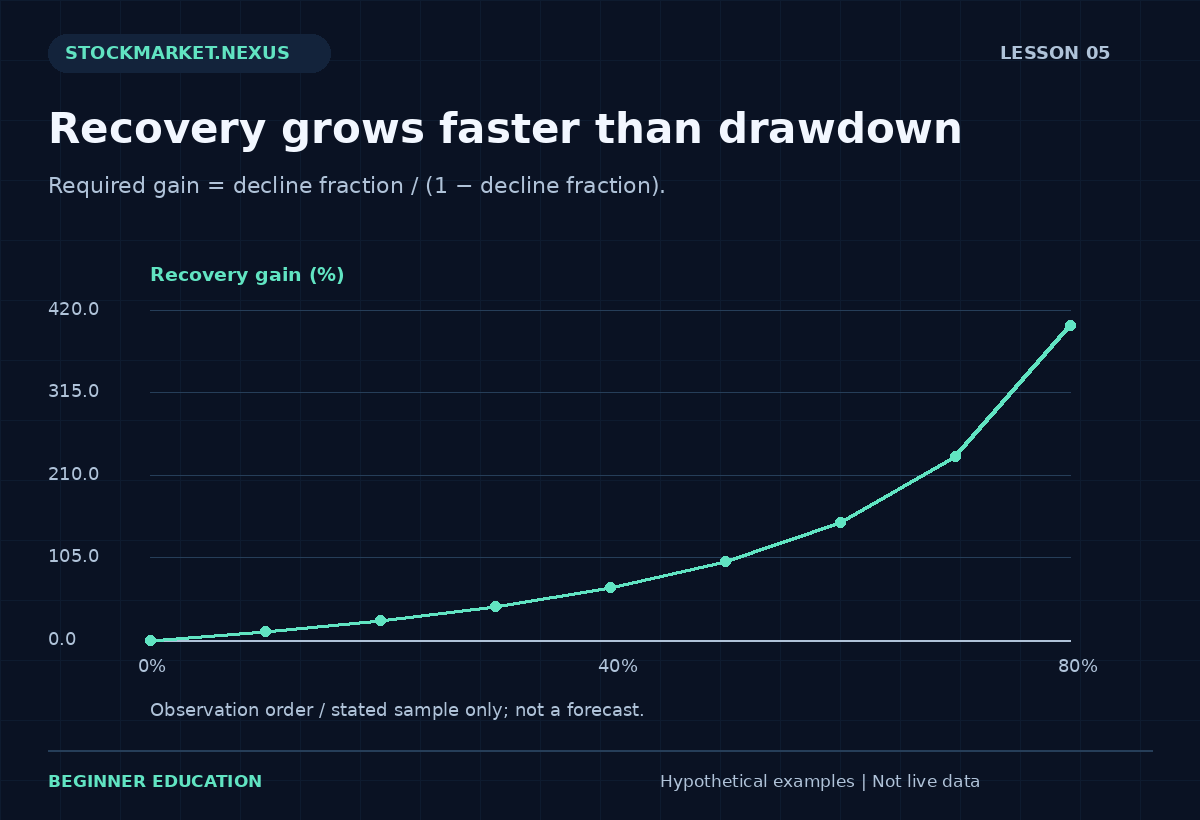
3. Calculate the required recovery gain
Required dollar recovery is the same dollar gap, but the percentage gain divides by the smaller current value. For $8,000 to reach $10,000, the required gain is $2,000/$8,000 = 25%. The same dollar amount has a different percentage because the base changed.
In terms of a fractional drawdown d below 100%, recovery fraction is d divided by one minus d. A 10% drawdown requires about 11.11%; a 25% drawdown requires 33.33%; a 50% drawdown requires 100%. The relationship becomes steeper as the decline grows.
At zero current equity, a percentage recovery from that base is undefined. The worksheet reports that clearly rather than displaying a finite promised gain. New funding would be a separate cash flow, not investment performance that magically repairs the denominator.
4. Separate recovery arithmetic from a recovery plan
A calculated 25% gap does not establish a sensible way to pursue it. Increasing leverage, widening exits, or taking larger positions to recover faster changes exposure and can deepen the drawdown. The arithmetic describes the gap; it does not recommend a response.
A review should first reconcile what produced the decline: market movement, costs, concentration, execution, rule violations, or a combination. Those causes call for different operational questions. An account’s emotional need to return to a prior number does not improve the economics of the next opportunity.
The risk journal lesson separates process compliance from outcomes. This helps prevent recovery pressure from becoming the main reason for a new trade.
5. Distinguish current drawdown from maximum drawdown
Current drawdown measures the gap from a relevant prior peak to the current value. Maximum drawdown over a historical path is the largest peak-to-later-trough decline under a stated convention. Two endpoints alone cannot establish the maximum decline that occurred between them.
An account may have recovered to $9,000 after falling to $6,000 from a $10,000 peak. Current drawdown is 10%, while the earlier maximum decline in that segment was 40%. Reporting only the current gap would omit the more severe path.
The dedicated exercise intentionally does not calculate maximum drawdown from two values. A professional tool should say when the required ordered history is missing rather than inventing a path statistic from insufficient data.
6. Use the dedicated recovery exercise
Open the Lesson 5 drawdown exercise. Enter peak 10000 and current equity 8000. Predict decline 2000, drawdown 20%, and required gain 25%. The visual compares the peak, current value, and recovery gap.
Change current equity to 5000. Drawdown is 50% and required gain 100%. Next use 9000. Drawdown is 10% and required gain about 11.11%. These examples make the asymmetry visible without implying a probability or timetable.
Finally set current to zero. The dollar gap remains $10,000, but the percentage recovery is undefined. Set current above the old peak to see the no-drawdown case. Explaining these edge cases is part of understanding the denominator, not an optional mathematical detail.
7. Handle deposits and withdrawals separately
A deposit can raise account equity without representing a market gain. A withdrawal can lower it without representing a trading loss. Comparing raw account values across cash flows can therefore misstate performance or drawdown if the convention is not adjusted appropriately.
A complete report needs dated cash flows and a stated return methodology. The simple worksheet assumes no external flows between its reference values. It should not be used to label a deposit-funded increase as a successful recovery strategy.
Keep a ledger of cash movements alongside trading records. If a chart platform’s equity curve omits flows or uses a different convention, reconcile the difference before comparing results. Data definitions matter as much here as they do in a price indicator.
8. Connect drawdown to sequence and exposure
A series of losses changes the capital base available for later decisions. Fixed-dollar losses and fixed-fraction losses produce different paths because one holds the loss amount constant while the other recalculates it from changing equity. Neither path is a prediction.
The losing-streak exercise explores that distinction under explicitly simplified assumptions. It does not estimate the chance of a streak or eliminate larger losses caused by execution deterioration.
A wider account review also considers whether several holdings can decline together. A modest single-position plan can coexist with a substantial portfolio drawdown when exposures overlap. The aggregate risk lesson keeps that combined scenario visible.
9. Case review: equal percentages, unequal dollars
Start at $10,000, lose 20%, then gain 20%. The path is $10,000 to $8,000 to $9,600. Reverse the order and the path becomes $10,000 to $12,000 to $9,600. With these two simple compounded returns and no cash flows, the ending value matches even though the intermediate experience differs.
The example illustrates both multiplicative arithmetic and path context. A learner who reports only “plus 20 and minus 20” misses the ending loss. A learner who reports only the endpoint misses the different interim peaks and drawdowns.
For practice, calculate each dollar change and label its base. Then explain why a required recovery gain is a measurement rather than a target that should override risk controls. The professional objective is to understand the account path and improve the review process, not to force the market to return capital by a chosen deadline.
Review challenge: the current gap hides an earlier trough
A fictional account starts at a $12,000 peak, falls to $7,200, and later reaches $10,800. Current drawdown against the peak is 10%, with an 11.11% required gain to regain it. The earlier trough represented a 40% decline and required a 66.67% gain from that lower base.
The two endpoint exercise can correctly calculate the current gap while lacking enough information to discover the earlier trough. A journal that retains the ordered equity history can report both. This is an example of scope, not a contradiction between calculations.
Now imagine a $1,000 deposit occurred before the current value was measured. The raw increase includes outside funding. The simple no-flow worksheet cannot separate that funding from investment performance, so a complete report needs the dated cash movement and a stated methodology.
For practice, write the peak, trough, current value, and any external flows on separate lines. Identify which question each calculation answers. Avoid calling the required recovery percentage a trading objective that must be achieved quickly. It is a measurement of the gap under a chosen base. A disciplined review investigates the causes and process implications of the decline before selecting a new exposure, rather than allowing the prior peak to dictate the next decision.
A complete practice record: assumptions, calculation, and review
Start the exercise by copying its inputs into a short record before pressing Calculate. Identify every unit and denominator: dollars, shares, percentages, price units, or a count of completed observations. Write the valuation time and clarify whether the values are fictional, historical, or confirmed transactions. The defaults in this course are fictional teaching examples. Their purpose is to make the arithmetic reproducible, not to recommend a position, percentage, boundary, or financing arrangement for a particular person.
Name the assumption that has the greatest effect on the answer. In one exercise it may be an exit fill; in another it may be the portfolio value, a shared shock, a cost, or the definition of the risk unit. A precise result can be highly sensitive to one uncertain input. State that sensitivity in plain language rather than allowing a clean screen to imply certainty. The calculator can enforce numerical consistency, but it cannot verify that the source data or chosen policy fits a real account.
Predict the result of one controlled change before calculating again. Keep every other input fixed. Explain whether the change affects a numerator, denominator, quantity constraint, cost, or scenario branch. Then compare the displayed result with your prediction. If they differ, return to the definition and arithmetic before inventing a market explanation. This method teaches the relationship among the inputs and prevents experimentation from becoming a search for a reassuring output.
Test a boundary case deliberately. Ask what happens when no whole share fits, a denominator becomes zero, a list is incomplete, a quantity exceeds the holding, or a scenario no longer matches the required price ordering. A validation message is useful evidence about the model’s scope. Do not replace a rejected value with an unrelated number simply to obtain an answer. First identify the violated assumption and decide whether this exercise is the appropriate model for the question.
Keep intended actions separate from confirmed states. A submitted order is not a completed fill, a cancellation request is not necessarily a canceled instruction, and a chart reference is not an available transaction price. For a paper exercise, state the hypothetical execution assumption. For a completed transaction record, use actual quantities, prices, charges, and status. Reconcile partial fills and remaining instructions so the ledger describes the exposure that exists rather than the exposure that was intended.
Write both the ordinary scenario and an adverse alternative when the model permits it. Preserve the original quantity while testing a worse outcome unless the purpose is explicitly to design a new plan. Label any revised plan with its own time and assumptions. A stress case is one selected possibility; it is not automatically the worst conceivable outcome or an estimate of probability. Missing information should remain labeled as missing rather than being converted into a zero or a favorable assumption.
Review the result on two separate dimensions. The first is outcome: what net dollars or normalized result occurred under the stated convention? The second is process: were the original definitions, constraints, and reconciliation steps followed? A favorable outcome does not prove a deviation was sound, and a loss does not prove that correct arithmetic was wrong. This separation helps a beginner identify a specific improvement instead of responding to every result with a new rule.
Finish with a concise explanation containing the observation, calculation, interpretation, and limitation. Another reader should be able to reproduce the important numbers without guessing what the fields mean. Preserve the original record, later revisions, and unfavorable examples. If extending the exercise into a historical or forward paper study, define the eligible sample and review horizon before collecting outcomes. A selected group of attractive examples cannot establish the reliability of a process. The strongest learning result is a clearer, auditable decision routine, including a clear reason when an example remains unresolved or does not fit the entered constraints.
Sources and model scope
Primary investor-education background supplies additional context. The numerical cases, graphics, and worksheets here are original fictional teaching examples. Every calculation depends on its stated convention; no worksheet determines personal suitability, guarantees execution, or establishes future returns.