


Options Trading · Lesson 13 of 15 · Reviewed November 10, 2026
A debit vertical spread buys one option and sells another of the same type and expiration on the same underlying, using different strikes and a net premium outlay. The short leg reduces the initial debit but also caps part of the favorable expiration payoff. It introduces assignment and management considerations absent from a standalone purchased option.
This lesson models standard one-for-one verticals with a 100 multiplier. The theoretical expiration formulas assume the structure remains intact under matching terms. They are not guarantees that every exercise, assignment, liquidation, or legging sequence will produce the same account path.
1. Identify a bull call spread
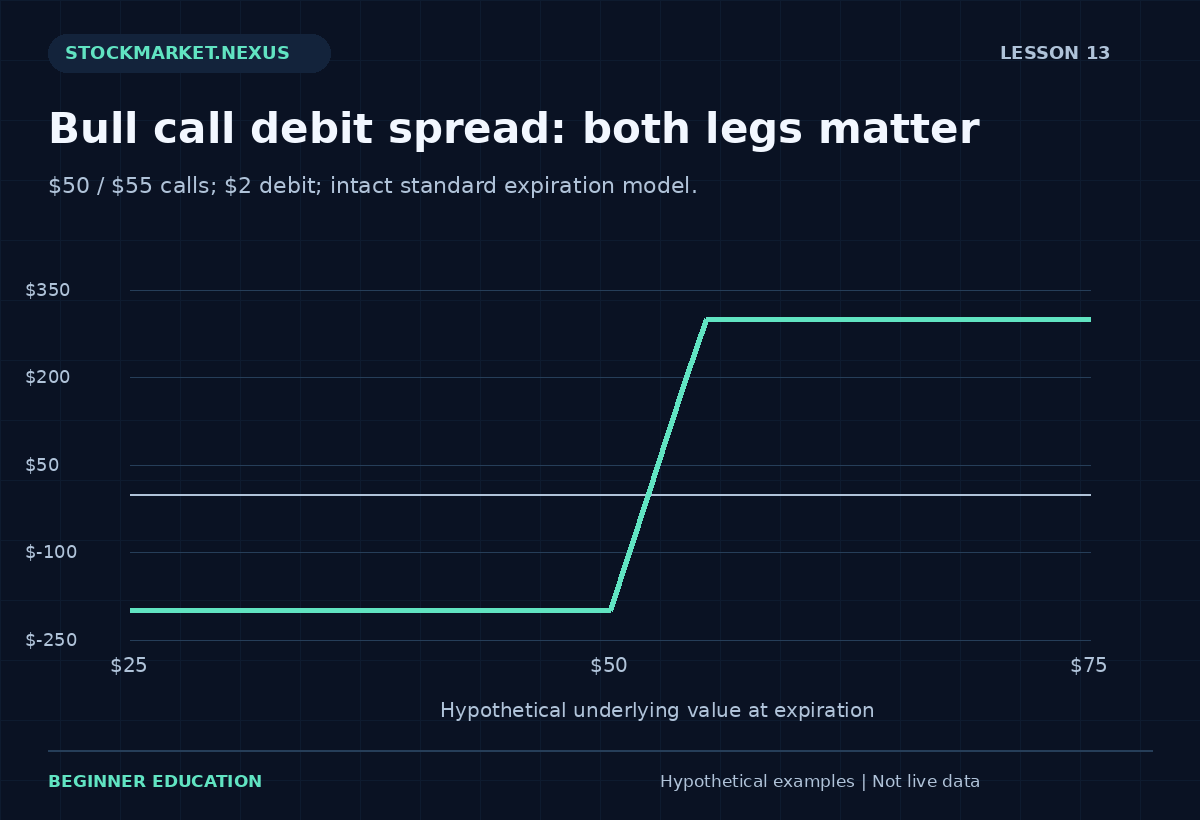
A bull call spread buys a lower-strike call and sells a higher-strike call with the same expiration. Consider a fictional long $50 call and short $55 call for a $2 net debit per share. One standard spread costs $200 before charges, and its strike width is $5.
At expiration, the long call's intrinsic value is reduced by the short call's intrinsic obligation. The resulting spread value is bounded between zero and the $5 width in the simplified model. Subtract the $2 debit to obtain the modeled profit or loss.
The long-call lesson provides the first component. The spread must be evaluated as two signed legs rather than treating the short premium as a discount with no corresponding obligation.
2. Calculate bull call expiration boundaries
With the $50/$55 strikes and $2 debit, modeled maximum loss is $200 per standard spread before charges. Maximum gain is $300: width minus debit, multiplied by 100. Breakeven is $52 before charges.
At an underlying value of $49, both calls have zero intrinsic value and the result is minus $200. At $53, spread value is $3 and profit is $100. At $60, the long and short intrinsic components differ by $5, producing the capped $300 gain after debit.
Theoretical upside is capped because the short call offsets further appreciation above its strike. A later stock rally does not restore the standalone long call's unlimited theoretical upside. The cap was part of the structure selected at entry, not an unexpected management problem.
3. Identify a bear put spread
A bear put spread buys a higher-strike put and sells a lower-strike put with the same expiration. A fictional long $55 put and short $50 put for a $2 debit also has a $5 width. Its favorable direction is downward under the expiration geometry.
Maximum modeled loss is the $200 debit per standard spread, while maximum gain is $300 before charges. Breakeven is $53: long put strike minus debit. At $60 the spread expires with zero intrinsic value; at $52 it has $3 value; at $45 it reaches its $5 capped value under the model.
The long-put lesson explains why the purchased put gains intrinsic value below strike. The short lower-strike put limits the combined favorable payoff and carries its own assignment obligation.
4. Keep expiration value separate from an early closing quote
Before expiration, a spread's resale value depends on both option quotes and changing pricing inputs. It is not always equal to its current intrinsic difference. A midpoint derived from two wide markets is a reference, not a guaranteed executable net price.
Use a consistent convention for the opening debit and closing credit. The realized spread result is received closing value minus paid opening value, scaled by multiplier and quantity, less applicable charges. Do not mix a favorable theoretical midpoint at entry with an assumed best execution at exit.
The option-chain lesson explains quote timing and size. Multi-leg order support can help express an intended net price, but acceptance does not guarantee a fill or eliminate every operational risk.
5. Understand the short leg's assignment consequences
A short American-style option can be assigned before expiration. The long leg does not necessarily exercise automatically to offset that event. The account may need resources or another action to manage resulting shares or obligations. Verify the broker's procedures rather than assuming the payoff chart administers the position.
Expiration near one strike can create uncertainty about which legs exercise or assign. A spread expected to settle to a neat net amount can leave an underlying exposure if the actual events differ. Closing before expiration requires a confirmed transaction; an unfilled request does not remove the issue.
The exercise and expiration lesson develops these transitions. Describe maximum loss as a theoretical intact-spread expiration boundary with assumptions, rather than a blanket guarantee for every possible account event.
6. Practice the structure one leg at a time
Use the debit-spread exercise to choose bull call or bear put, lower strike, upper strike, net debit, quantity, and terminal underlying value. Calculate each intrinsic component and the combined result.
Test below both strikes, between them, and above both. The favorable side changes between bull call and bear put, while the width-minus-debit cap remains the same under the matching standard model. A debit greater than the width should be rejected by the simplified worksheet as outside its intended coherent inputs.
Finally, write what happens if the short leg is assigned while the long leg remains open. That account-state question is separate from the expiration formula. A learner has understood the spread only when both the signed payoff and the operational exception can be explained.
## Worked bull call spread in three regions
For a long $50 call and short $55 call entered at a $2 net debit, examine underlying expiration values of $45, $53, and $60. The long-call intrinsic values are zero, $3, and $10; the short-call intrinsic obligations are zero, zero, and $5. Net spread values are therefore zero, $3, and $5 per share.
Subtract the $2 debit to obtain minus $200, plus $100, and plus $300 per standard spread before charges. This leg-by-leg calculation explains the cap rather than asking the learner to memorize it. Above the higher strike, both call components grow together in the simplified intrinsic model, leaving a fixed difference.
Add a fictional $4 total charge per completed spread. Maximum modeled loss becomes $204 and maximum gain becomes $296. The simple expiration breakeven rises from $52 to $52.04 for one standard spread. Charges change the transaction result without changing the strikes or the width.
Worked bear put spread in three regions
For a long $55 put and short $50 put at a $2 debit, use underlying values of $60, $52, and $45. Long-put intrinsic values are zero, $3, and $10, while short-put obligations are zero, zero, and $5. The net values again become zero, $3, and $5, but the favorable direction is downward.
The contract-dollar results before charges are minus $200, plus $100, and plus $300. Breakeven is $53 before charges. With the same $4 total charge, the put spread needs an expiration value of $52.96 to cover the full debit and charge in the middle region.
This comparison shows why type and leg direction must be explicit. The same width and debit can produce mirrored directional geometry. A worksheet that uses only the words debit spread without specifying which option is long and which is short is missing information needed to interpret the payoff.
Compare early closure with the expiration table
Suppose a spread bought for $2 can later be sold for a $2.80 net credit. One standard spread realizes $80 before charges. That result comes from actual or explicitly modeled premium fills, not from the underlying's current intrinsic difference alone. Remaining extrinsic value and market conditions can affect both legs.
A quoted net midpoint is not a guaranteed execution. If historical data do not provide executable spread prices, state the convention and limitation. Do not assume a favorable midpoint at entry while using a different convention to improve the exit. Consistency is necessary before a performance comparison has meaning.
If only one leg closes, the account no longer holds the intended intact vertical. Record the remaining contract and its obligation. Separate-leg execution can create exposures outside the original diagram, so the journal must preserve the sequence rather than only the strategy's final label.
Audit theoretical limits and operational exceptions separately
The width-minus-debit gain and debit-loss boundaries describe the matched expiration structure under the model. Early assignment, unequal exercise, financing, and broker actions can create different intermediate holdings or costs. A professional lesson should not erase those branches when using the phrase limited risk.
Write a scenario where the short option is assigned and the long remains open. Identify the resulting shares or delivery obligation and the still-owned option. The learner does not need to submit any action to recognize that the account state requires verification and a plan.
Then return to the intact payoff table and explain what assumptions restore its simple geometry. This two-part audit allows the formula to remain useful without being oversold. The mathematical structure and the operating process are related, but neither can substitute for understanding the other.
## How to complete and review the lesson exercise
Start by writing the contract identity and the calculation's time horizon before entering numbers. A quoted premium, a hypothetical expiration value, and a strike-related cash transaction are different inputs. State which one the exercise uses. This prevents a correct arithmetic operation from answering the wrong question. The worksheet should support the lesson's definitions rather than encourage the visitor to infer a real trade from an attractive output.
Next, translate every per-share figure into the stated contract units. Use the actual multiplier and deliverable when studying a real specification; the lesson exercises intentionally use clearly labeled standard examples. Keep quantity separate from price. Increasing contract count changes total dollars and obligations without improving the underlying hypothesis. A small premium displayed on a chain can therefore become a material aggregate amount when multiplied across several contracts.
Use three input checks before interpreting the result. First, confirm that the option type and position direction match the intended lesson. Second, confirm that the premium, strikes, and quantity are internally coherent under the exercise's model. Third, distinguish a supplied scenario from an estimated probability. A table of possible outcomes does not assign odds to its rows, and a local sensitivity calculation does not forecast which input change will occur.
Record charges under one consistent convention. If actual entry and closing premiums already reflect the bid and ask, do not subtract the same spread again as an additional explicit fee. If the exercise begins with reference prices instead, label any separate friction assumption. The distinction is especially important when comparing several examples: a strategy should not receive favorable midpoint fills while an alternative is evaluated with less favorable executable quotes.
After calculating, describe the account state in plain language. State whether the model refers to an owned option, a short obligation, a matched combination, a completed premium transaction, or a possible underlying purchase or delivery. A numerical result is incomplete if the learner cannot identify what remains held or owed. Exercise and assignment can create a different position from the one shown on the original option payoff chart.
Repeat the exercise with one adverse change and one favorable change while keeping the other supplied inputs fixed. This is a controlled comparison for learning mechanics, not evidence of a real-market distribution. Preserve both results. Do not remove an unfavorable example because it makes the strategy less appealing, or reinterpret the original terms after seeing which alternative would have performed better.
Finally, separate the model's conclusion from the facts it does not establish. A simplified expiration calculation can explain economic geometry without reproducing early exercise, broker liquidation, unavailable execution, taxes, dividends, financing, or every temporary account state. A Greek worksheet can teach units without implementing a complete pricing model. The relevant omissions are specific limitations of the exercise, not reasons to ignore the calculation or to treat it as more complete than it is.
A useful review contains the original inputs, the formula or rule applied, the contract-dollar result, the remaining account-state question, and one correction if an error occurred. Keep process compliance separate from whether the chosen scenario was profitable. The objective is a reproducible explanation that another reader can audit. Repeating a known example can improve fluency, but it does not certify real-money readiness or establish future returns.
## Sources and further reading
Primary educational reference provides background. Review the OCC options disclosure document for standardized-option characteristics and risks. Numerical examples and worksheets in this lesson are fictional educational illustrations.