


Options Trading · Lesson 03 of 15 · Reviewed November 10, 2026
A purchased call gives its holder the contractual right to buy the specified underlying deliverable at the strike under the exercise terms. The buyer pays a premium. The option can lose all its value, and a correct directional view can still produce a losing trade if the move is too small, too late, or accompanied by unfavorable changes in other pricing inputs.
This lesson models a fictional long call with a $50 strike, $3 premium per share, and a standard 100 multiplier. It evaluates expiration economics separately from a resale before expiration. The payoff illustration does not assume that the account should exercise or can fund a resulting stock purchase.
1. Calculate the premium commitment
One contract at a $3 premium costs $300 before charges under the example multiplier. Two cost $600. The premium is the price paid for the option, not a refundable deposit. If the option expires without value, the buyer can lose that premium and applicable charges.
The underlying notional associated with a standard $50 call is different from the premium amount. Exercise can involve buying 100 shares for $5,000 per contract. Owning a call therefore does not mean the account already owns those shares or has already funded the exercise-related purchase.
The contract foundation lesson explains these separate cash flows. Preserve them on the decision card so the smaller initial outlay is not mistaken for the full amount of resources that could become relevant if exercise occurs.
2. Calculate intrinsic value at expiration
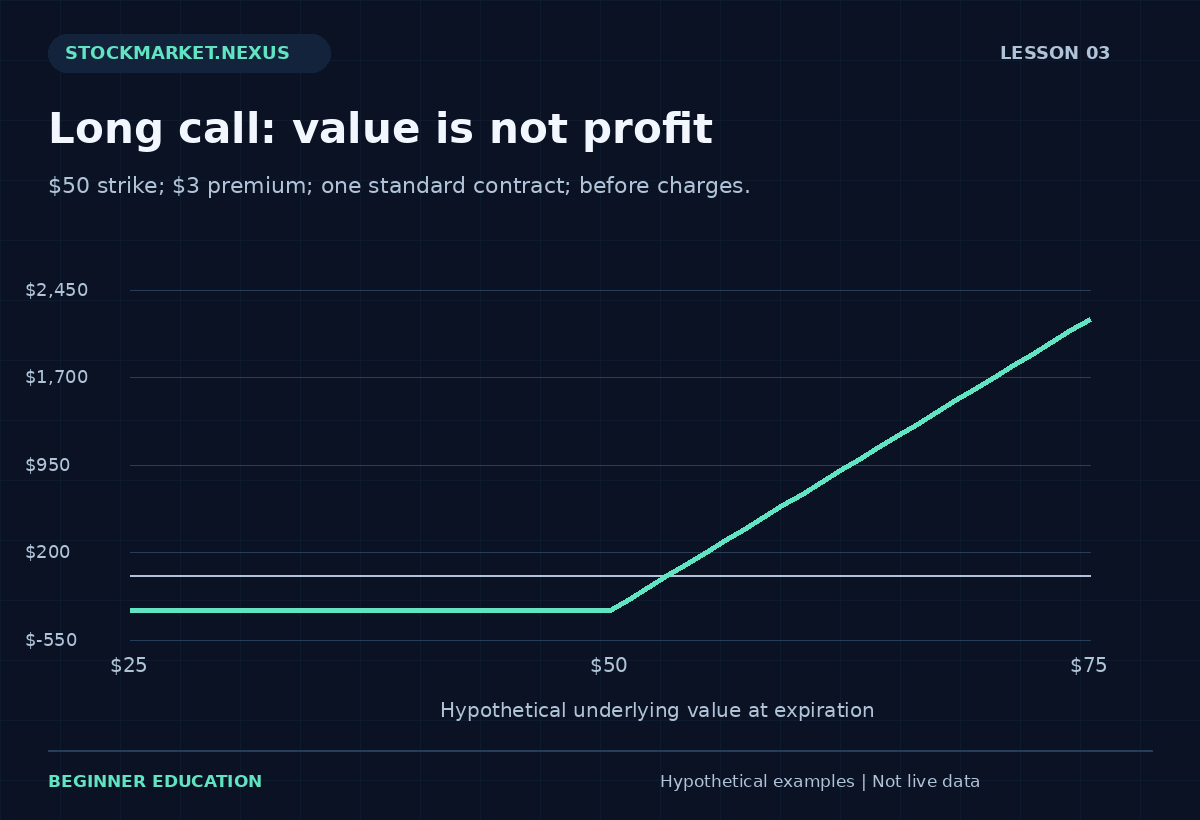
For the simplified expiration model, call intrinsic value per share is the greater of underlying value minus strike and zero. At $48, the $50 call has zero intrinsic value. At $52, it has $2. At $57, it has $7. The option's expiration value and the trade's profit are different quantities.
Subtract the $3 paid premium. At $48, the one-contract price result is minus $300. At $52, it is minus $100 despite the option being in the money. At $57, it is plus $400 before charges. Moneyness describes the relationship to strike; it does not tell the complete trade result.
The expiration breakeven is $53 before charges: strike plus paid premium. With a fixed total charge allocated to the modeled position, the required underlying value rises accordingly. Label the breakeven as an expiration calculation rather than a price that must be reached for every possible pre-expiration resale profit.
3. Keep resale value separate from expiration payoff
Before expiration, an option can include extrinsic value as well as intrinsic value. A long call bought at $3 and later sold at $3.60 earns sixty cents per share, or $60 per standard contract before charges. That premium change can occur while the underlying is below the expiration breakeven.
Conversely, a stock rise does not guarantee that the call's executable resale premium rises enough to produce profit. Remaining time, implied volatility, and current quotes can affect the outcome. A stale last premium should not be substituted for an available bid simply because it produces a more attractive result.
The intrinsic and extrinsic value lesson separates these components. An expiration chart is useful for contract economics, but it is not a complete pricing model for the option at every earlier date.
4. Understand timing and volatility exposure
A call thesis needs a time window. A stock rally after the contract expires cannot restore an expired right. A slower-than-expected move can also leave less extrinsic value in the option. The buyer's task is not merely to predict direction but to evaluate a contract whose remaining life is changing.
Implied volatility is another relevant input. If the option was purchased when premiums incorporated substantial uncertainty, a later reduction in that uncertainty can affect value even after a favorable stock move. Do not describe a long call as a pure leveraged substitute whose premium must move dollar for dollar with the shares.
The implied-volatility lesson develops event scenarios. A model sensitivity can help explain one input at a time, but real inputs can change together. A precise Greek value does not turn the position into a predictable outcome.
5. Define an exit plan before purchase
The decision card should state the contract identity, maximum acceptable premium, quantity, total premium at risk, review dates, and intended closing method. Add a procedure for approaching expiration. A plan to sell before expiration requires a confirmed closing fill, not merely a submitted order or an alert.
A stop instruction on the option may face wide spreads and changing liquidity, and supported behavior varies by broker. A mental premium threshold also requires attention and an available execution. Neither should be described as a guaranteed way to preserve a particular fraction of premium.
If the option remains open near expiration, verify exercise procedures and potential stock-purchase resources. The limited loss of the standalone purchased option is not a blanket description of a new stock position created by exercise. The account transition can introduce a different exposure that requires its own plan.
6. Practice both favorable and unfavorable paths
Use the long-call practice exercise to enter a strike, premium, quantity, and hypothetical expiration value. Compare values below strike, between strike and breakeven, and above breakeven. The middle region is especially useful because it shows an in-the-money option with a losing premium investment.
Next, calculate a resale using a different premium and keep that result in a separate row. Do not use an expiration intrinsic-value formula to price an earlier sale. The worksheet should clearly say whether it describes expiration economics or a quoted closing transaction.
Finally, write the account state if the call is sold, expires without exercise, or is exercised. Those are different endings. A beginner has understood the position only when the rights, premium result, and possible stock transition can all be explained without relying on the word bullish.
7. Compare quantity without changing the market hypothesis
Moving from one contract to five multiplies premium exposure under the same terms. It does not improve the chance that the underlying reaches a desired level. For the $3 example, five contracts commit $1,500 in premium before charges and can involve 500 shares under standard physical exercise.
A small quoted premium can therefore represent substantial aggregate exposure. Always calculate total dollars and deliverable before interpreting a percentage change. A 20% premium loss means different money for one contract and for twenty contracts, even though the chart displays the same percentage.
The review should classify outcome and process separately. A profitable call entered outside the written premium boundary is still a process deviation. A compliant call that expires worthless remains part of the method's outcome evidence. Do not rewrite the contract choice after observing which expiration would have performed best.
## Worked expiration table: an in-the-money loss
Use one fictional $50 call purchased for $3 with a 100 multiplier. At underlying expiration values of $45, $50, $52, $53, and $58, intrinsic values per share are zero, zero, $2, $3, and $8. Subtracting premium gives contract results of minus $300, minus $300, minus $100, zero, and plus $500 before charges.
The $52 row is the key diagnostic. The call is in the money, but the buyer has not recovered the full premium. A learner who labels that row profitable is confusing option value with trade result. Keep strike, intrinsic value, paid premium, and net result in separate columns.
Add a fictional $2 total charge to the completed position. The results all decrease by $2, and the simplified expiration breakeven becomes $53.02 for one standard contract. Charges affect the transaction result, while the call's moneyness boundary remains the $50 strike. The two boundaries answer different questions.
Compare a premium sale with exercise economics
Suppose the same call can be sold before expiration at a $3.60 bid. Selling one standard contract realizes $360 of premium proceeds, compared with the $300 paid, giving $60 before charges. This is a premium transaction, not an exercise of the right to buy stock.
If the underlying reference is $52, simplified intrinsic value is $2 per share. Exercising and immediately valuing the acquired shares at that reference does not automatically capture the option's entire $3.60 quoted premium. Remaining extrinsic value, available execution, charges, and account resources matter to the comparison.
Do not turn the example into a universal instruction to sell or exercise. Its purpose is to identify different cash-flow paths. The account-specific decision requires actual contract terms, executable prices, and intended holdings. A worksheet should make those requirements recognizable without pretending to perform the real transaction.
Test a correct direction with an insufficient move
Imagine the underlying rises from $50 at entry to $52 at expiration. The directional view was favorable, but the $3 call loses $100 before charges under the example. Being right about direction did not establish the magnitude and timing needed to recover the premium.
Now imagine the stock reaches $58 only after the option has expired. The expired contract does not regain a right because the later price validates the old forecast. The journal should preserve the selected expiration rather than substituting a longer-lived contract after the outcome.
A third path can rise early and later retreat. Its expiration result may be poor even if an earlier closing opportunity existed. Whether the method would have taken that opportunity depends on its original exit rules and actual quotes. A retrospective choice of the best sale time is not evidence that the plan could have captured it.
Build a full-loss scenario without minimizing it
A purchased call can lose all its premium. A small per-share premium should therefore be scaled to the whole position before judging its significance. Ten contracts at $3 commit $3,000 before charges under a standard multiplier, even though the displayed premium is only three dollars.
Compare that commitment with the account's stated hypothetical allowance and other holdings. Several calls on related securities can also share market or event exposure. A premium-limited standalone loss does not imply that the combined account risk is small or diversified.
The practice record should retain quantity, total outlay, possible exercise resources, and the intended closing deadline. These are concrete checks. They make the educational example more useful than a dramatic percentage-gain illustration that shows the favorable branch while leaving the full-premium loss and account transition unexplained.
## How to complete and review the lesson exercise
Start by writing the contract identity and the calculation's time horizon before entering numbers. A quoted premium, a hypothetical expiration value, and a strike-related cash transaction are different inputs. State which one the exercise uses. This prevents a correct arithmetic operation from answering the wrong question. The worksheet should support the lesson's definitions rather than encourage the visitor to infer a real trade from an attractive output.
Next, translate every per-share figure into the stated contract units. Use the actual multiplier and deliverable when studying a real specification; the lesson exercises intentionally use clearly labeled standard examples. Keep quantity separate from price. Increasing contract count changes total dollars and obligations without improving the underlying hypothesis. A small premium displayed on a chain can therefore become a material aggregate amount when multiplied across several contracts.
Use three input checks before interpreting the result. First, confirm that the option type and position direction match the intended lesson. Second, confirm that the premium, strikes, and quantity are internally coherent under the exercise's model. Third, distinguish a supplied scenario from an estimated probability. A table of possible outcomes does not assign odds to its rows, and a local sensitivity calculation does not forecast which input change will occur.
Record charges under one consistent convention. If actual entry and closing premiums already reflect the bid and ask, do not subtract the same spread again as an additional explicit fee. If the exercise begins with reference prices instead, label any separate friction assumption. The distinction is especially important when comparing several examples: a strategy should not receive favorable midpoint fills while an alternative is evaluated with less favorable executable quotes.
After calculating, describe the account state in plain language. State whether the model refers to an owned option, a short obligation, a matched combination, a completed premium transaction, or a possible underlying purchase or delivery. A numerical result is incomplete if the learner cannot identify what remains held or owed. Exercise and assignment can create a different position from the one shown on the original option payoff chart.
Repeat the exercise with one adverse change and one favorable change while keeping the other supplied inputs fixed. This is a controlled comparison for learning mechanics, not evidence of a real-market distribution. Preserve both results. Do not remove an unfavorable example because it makes the strategy less appealing, or reinterpret the original terms after seeing which alternative would have performed better.
Finally, separate the model's conclusion from the facts it does not establish. A simplified expiration calculation can explain economic geometry without reproducing early exercise, broker liquidation, unavailable execution, taxes, dividends, financing, or every temporary account state. A Greek worksheet can teach units without implementing a complete pricing model. The relevant omissions are specific limitations of the exercise, not reasons to ignore the calculation or to treat it as more complete than it is.
A useful review contains the original inputs, the formula or rule applied, the contract-dollar result, the remaining account-state question, and one correction if an error occurred. Keep process compliance separate from whether the chosen scenario was profitable. The objective is a reproducible explanation that another reader can audit. Repeating a known example can improve fluency, but it does not certify real-money readiness or establish future returns.
## Sources and further reading
Primary educational reference provides background. Review the OCC options disclosure document for standardized-option characteristics and risks. Numerical examples and worksheets in this lesson are fictional educational illustrations.