

Relative strength is not RSI
Relative-strength momentum in this example compares a stock's price return with a benchmark's price return over the same 20-session interval. It is not the Relative Strength Index oscillator. The similar wording can confuse beginners into treating RSI above 50 as proof that a stock outperformed an index. Those are different calculations answering different questions.
This long-side rule requires a positive stock return, an outperformance difference of at least five percentage points, a close above SMA50, and a fresh preceding-20-high breakout. The relative-return condition is context. The price breakout is the entry event. A long-standing leader without a new crossing does not automatically create a fresh setup under this version.
Align dates and return basis
Use start and end closes from identical dates for the stock and benchmark. A 20-session stock interval cannot be compared fairly with a benchmark's calendar month or a feed delayed by one session. Record the benchmark identifier, exchange calendar, source, and close convention. A missing observation should remain unresolved rather than being filled from an unmatched date without disclosure.
This exercise compares price returns, not total returns. A total-return series including reinvested dividends is a different basis and must not be mixed casually with a price-only benchmark. Corporate-action adjustments must also be consistent. A split can create a fictitious collapse or surge if the start and end prices are not expressed on the same basis.
Calculate percentages and percentage points correctly
Stock return is (end / start − 1) × 100. Benchmark return uses the same formula. Their difference is measured in percentage points, not a percent increase in one return relative to the other. A stock gaining 10% while a benchmark gains 4% outperforms by six percentage points. Dividing 10 by 4 and describing the result as the strategy's required outperformance would be a different calculation.
The example requires the stock's own return to be positive as well. A stock down 5% can outperform a benchmark down 15% by ten percentage points while still having a negative price return. That might interest a different relative-value or defensive strategy, but it fails this positive-momentum version.
Combine context with a fresh event
The current stock close must exceed SMA50 and the highest high of the preceding 20 completed sessions. The prior close must not have exceeded its own preceding-20 high. Current and previous channel references are evaluated on shifted windows, excluding each tested bar. Reusing a single latest high for both comparisons can misclassify the event.
These price conditions are derived from the same stock history as the stock return. They are not independent confirmations in a statistical sense merely because they have different names. The guide states them as filters of one experiment, without claiming that multiplying their apparent agreement produces a reliable probability.
A complete fictional comparison
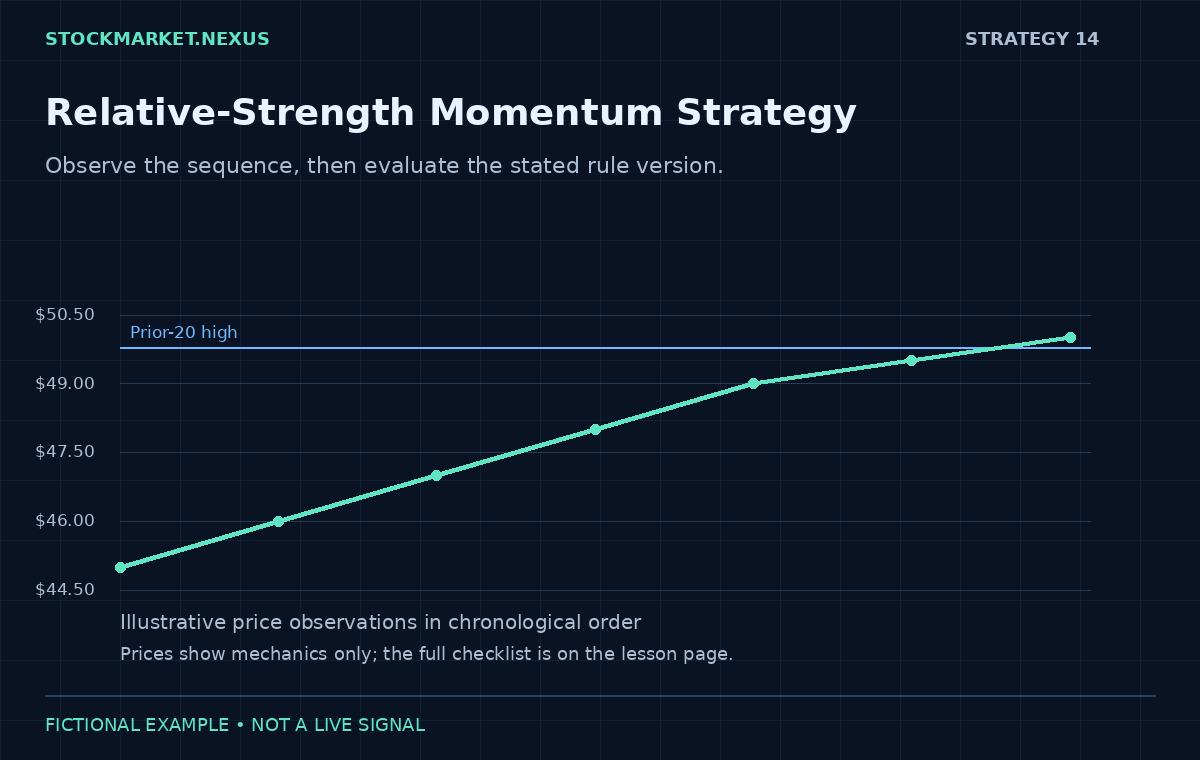
Suppose the stock rises from $45 to $50 while the benchmark rises from 100 to 104 over the same 20 sessions. The stock price return is approximately 11.11%, the benchmark return is 4%, and the difference is approximately 7.11 percentage points. The stock is positive and exceeds the five-point outperformance threshold.
If SMA50 is $48, the preceding-20 high is $49.80, the prior close is $49.50, and the prior close's own reference was $49.80, the trend and fresh crossing conditions pass. A hypothetical next-session entry at $50 with ATR14 at $1 gives an initial stop of $48.50 and a two-distance target of $53. Costs and friction change the net scenario arithmetic.
Change benchmark end to 110. The benchmark now gains 10%, reducing stock outperformance to about 1.11 percentage points, so the relative-return filter fails. Alternatively, keep the benchmark but change the prior close to $50 against its $49.80 reference. Relative leadership remains, but the supposed fresh breakout is not fresh. These are different reasons to reject the example.
Concentration can hide behind strong rankings
Several leading stocks may belong to the same sector or share a common economic driver. Passing individual-stock filters does not establish a diversified portfolio. A ranking can also change quickly after an event or when its oldest observation rolls out. The exercise checks one stock/benchmark comparison, not aggregate correlated exposure.
A full implementation should define whether sector benchmarks or a broad index are used, how symbols enter the universe, and how delisted instruments are treated. Selecting today's surviving leaders and examining only their past charts creates hindsight. Preserve the point-in-time universe before making performance claims about a momentum screen.
Exits and practical review
The protective reference takes priority, followed by the fixed target, a completed daily close below SMA50, and a ten-session time exit. This version does not exit solely because the relative-return ranking changes. Adding such a rule would create a different strategy, requiring its own timestamp and reference window.
The dedicated tool displays both returns, their percentage-point difference, the event conditions, and position arithmetic. It asks explicitly whether the dates and return basis match. An attractive numeric difference with an unresolved date confirmation remains unresolved. The central lesson is to preserve the comparison's denominator and timing before interpreting the apparent strength of the result.
Versioned rule card
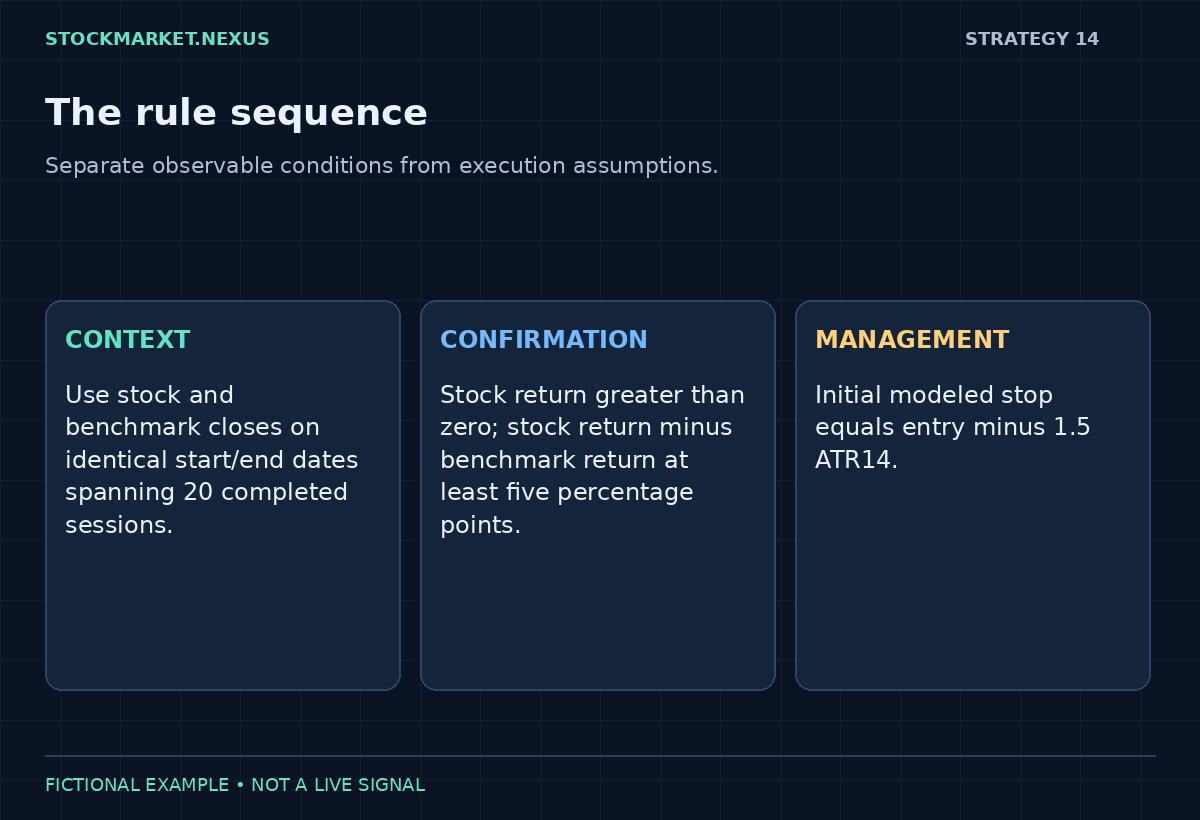
EDU-2026-11-v1. These illustrative settings define one educational experiment. They are not optimized parameters, a verified edge, or personal trade instructions.
Entry condition 1: Use stock and benchmark closes on identical start/end dates spanning 20 completed sessions.
Entry condition 2: Stock return greater than zero; stock return minus benchmark return at least five percentage points.
Entry condition 3: Current stock close above SMA50.
Entry condition 4: Current stock close above its preceding-20-session high; prior close at or below its own preceding-20 high.
Entry condition 5: Model next-session entry; account for sector and portfolio concentration outside this stock-level check.
Exit rule 1: Initial modeled stop equals entry minus 1.5 ATR14.
Exit rule 2: Target equals entry plus two times planned entry-to-stop distance.
Exit rule 3: Protective exit first; otherwise target, then daily close below SMA50, then ten-session time exit.
From a rule match to an executable paper plan
A strategy condition and an executable order are different objects. First record the completed observation that satisfied the condition. Then write the earliest moment at which that observation could have been known. A rule requiring the final daily close cannot normally be evaluated early enough to assume a fill at that same closing price. The next session may open above, below, or through the proposed reference. Intraday examples have the same sequencing issue at the boundary between a completed five-minute bar and the next bar. The hypothetical entry used in the exercise is a separate input for exactly this reason.
Write the order instruction before calculating a result. A market instruction emphasizes execution while allowing price uncertainty. A limit instruction imposes a price boundary while accepting nonexecution or partial execution. A stop reference is an activation condition, not an insurance contract. A stop-limit instruction can activate without filling. If a gap skips the reference, the chart does not prove that the position could have been closed at that reference. A realistic paper record therefore preserves the planned price, actual assumed fill, quantity filled, remaining quantity, and the reason for any cancellation. These distinctions are explained further in the site's Trading Basics lessons.
Quantity, costs, and a worked execution budget
For a hypothetical long position, planned price risk per share is entry minus stop. For a hypothetical short, it is stop minus entry. Both expressions must be strictly positive. Suppose a long entry is $50, a stop reference is $48.50, the total adverse-friction assumption is $0.05 per share across the round trip, and fixed round-trip charges are $2. With a modeled $100 loss budget, the arithmetic quantity is floor((100 − 2) / (1.50 + 0.05)), or 63 shares. This models $99.65 of loss at the assumed exit, rather than proving an actual maximum loss.
A separate cash check matters. If only $2,000 is allocated to the share purchase and charges, floor((2000 − 2) / 50) permits 39 shares in this simplified cash calculation. The smaller quantity governs the long example. With those 39 shares, a hypothetical $53 target and the same friction produce 39 × (3 − 0.05) − 2 = $113.05 of modeled net gain. The modeled stop loss is 39 × 1.55 + 2 = $62.45. Their ratio is approximately 1.81. That ratio describes two assumed outcomes; it says nothing about how likely either outcome is.
The exercise uses whole shares and a single fixed-friction assumption to keep the arithmetic visible. Borrow fees, financing, taxes, changing spreads, partial fills, market impact, and a stop skipped by a gap require additional treatment. In particular, the long cash-cap input is not a margin or buying-power model for a short position. Review aggregate exposure and correlated positions using the site's Risk Management learning path before treating any individual-position calculation as a complete portfolio plan.
Exit priority and ambiguous bars
The listed exits describe distinct reasons for leaving. The protective reference is checked first under the illustrative plan; a target or closing-bar condition is considered afterward. However, a daily or five-minute OHLC bar may contain both the stop and target without revealing which was reached first. Do not choose the favorable sequence simply because it improves a result. Use finer trustworthy observations, flag the sequence as unresolved, or apply a disclosed conservative convention consistently. A closing-bar exit cannot be assumed to have prevented an earlier intrabar stop touch.
If a target is fixed at confirmation, preserve that original value. If a strategy explicitly updates a trailing reference, record the update time and make the new value effective only afterward. A revised stop should never be applied retroactively to the bar that generated it. A time exit also needs an execution assumption: submitting an order at a chosen time does not establish that the observed chart price was the actual available fill. Record the difference instead of silently replacing the plan with hindsight.
Review evidence without manufacturing a track record
Start a paper test by freezing the rule version, instrument universe, session definition, time zone, data source, corporate-action treatment, and cost assumptions. Include every eligible observation, including failed conditions and unfilled orders. A collection of attractive screenshots is not a complete sample. Missing data should remain missing rather than being converted into a passing condition. The examples here illustrate mechanics and arithmetic; none of the chart paths establishes a historical win rate or expected future return.
If testing historical data later, separate development observations from a subsequent evaluation period. Record every parameter combination tried so that an attractive result is not presented as an independent discovery after many hidden trials. Include delisted instruments when the universe requires them, avoid using future information to select past leaders, and check how split and dividend adjustments affect price and volume comparisons. These details can change which bars qualify even when the indicator names remain identical. The Technical Analysis lessons provide related material on indicators, reference windows, and disciplined testing.
Using the dedicated practice exercise
Open the exercise linked to this strategy and first review the fictional defaults. Change one assumption at a time. The tool evaluates the supplied numbers and explicitly entered review states; it does not retrieve an independent chart or verify a person's judgment. “Meets entered example conditions” means only that the entered conditions satisfy this particular rule version. “Unresolved” identifies required information that has not been confirmed. A failed condition remains a failed condition even when the hypothetical target result is attractive.
After reviewing the result, preserve the inputs and write which observation changed the conclusion. Repeat with a near-boundary example, a missing requirement, and an adverse execution assumption. Reset restores the fictional example. The worksheet does not send orders, connect a broker, or save a trading account. A repeatable process includes decisions to wait, reject a setup, or investigate an unknown; it is not a requirement to produce a trade every session. The Trading Psychology lessons explain how to review those decisions independently of profit and loss.
Indicator background
For indicator definitions, see Fidelity’s Technical Indicator Guide. The particular thresholds and combinations on this page are our illustrative rule version, not a strategy endorsed or validated by that reference.